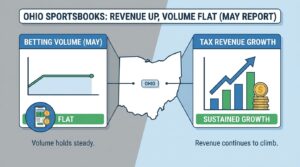
Ohio’s regulated sports betting market delivered a notable tax haul in May 2024, even as total wagering volume remained essentially unchanged from the prior month. The Ohio Casino Control Commission reported that sportsbooks generated steady state revenue, underscoring operator efficiency in converting handle into taxable income. What makes the result interesting is not the raw numbers themselves but the widening gap between betting activity and the revenue it produces for the state.
What Ohio’s May Betting Numbers Signal for Operators and the State
The surface-level story here is stability. But underneath, the data reveals a market maturing in ways that matter to both regulators and the operators competing for share. Here are the strategic takeaways:
- Tax revenue held firm or grew slightly in May, despite total handle showing minimal month-over-month movement
- Operator hold rates appear to be improving, meaning sportsbooks are retaining a larger share of each dollar wagered
- Promotional spending, which erodes taxable revenue, may be declining as the market exits its aggressive customer-acquisition phase
- Ohio continues to benefit from a broad licensing framework that keeps multiple operators active and competitive
- The state’s 10% tax rate on sports betting revenue remains one of the more moderate structures in the Midwest
Handle Steady, Revenue Up: How?
When betting volume stays flat but tax receipts climb, the explanation almost always sits in one of two places: hold percentage or promotional credit reduction. In Ohio’s case, both forces appear to be at work simultaneously.
Hold percentage refers to the share of total wagers that sportsbooks keep after paying out winners. A higher hold means more gross gaming revenue per dollar bet. Across the U.S., mature markets tend to see hold rates stabilize in the 8–10% range for online sportsbooks, up from the 5–7% range common during launch periods when operators lean heavily on risk-free bets and odds boosts to attract users.
And while Ohio launched legal sports betting in January 2023, the market is now roughly 17 months old. That timeline tracks with the pattern seen in states like New Jersey and Pennsylvania, where promotional intensity peaked in the first 12–18 months before tapering. Fewer promotional credits flowing to bettors means more of the gross revenue becomes taxable.
A Quieter Month on the Calendar Still Delivered
May sits in an awkward spot on the sports calendar. The NFL draft is over. March Madness is long gone. The NBA and NHL playoffs carry some weight, but they don’t generate the broad, casual-bettor engagement that football season does.
Still, Ohio’s sportsbooks managed to keep the revenue engine running. That resilience matters. It suggests the state’s betting population has moved beyond event-driven spikes and toward more habitual wagering behavior (a distinction regulators have been slow to quantify but operators track closely). Baseball, in-play betting on NBA playoff games, and emerging markets like golf and tennis all contributed to sustaining volume through what is traditionally a softer period.
Where Ohio Sits Among Midwest Competitors
Ohio’s sports betting framework competes directly with neighboring states for both operator investment and bettor engagement. The competitive landscape is tightening.
| State | Tax Rate | Launch Date | Online Operators |
|---|---|---|---|
| Ohio | 10% | January 2023 | 16+ |
| Michigan | 8.4% | January 2021 | 15 |
| Pennsylvania | 36% | May 2019 | 18+ |
| Indiana | 9.5% | September 2019 | 12 |
Pennsylvania’s significantly higher tax rate generates more revenue per dollar of handle but also compresses operator margins, which can limit promotional spending and, arguably, long-term market growth. Ohio’s moderate rate has attracted a deep bench of licensed operators, and that breadth of competition tends to benefit consumers through better odds and more varied product offerings. Whether it maximizes state revenue over time is a question Columbus hasn’t fully answered yet.
The Operator Landscape and Market Maturity
Major operators like DraftKings’ Ohio sportsbook and FanDuel continue to dominate market share nationally, and Ohio is no exception. But the state’s licensing structure has also allowed smaller and regional brands to carve out niches, particularly through retail partnerships with casinos and racinos.
This diversity creates a more distributed revenue base for the state. It also means that when one operator pulls back on marketing spend, others may fill the gap, keeping overall market activity more stable than it would be in a two-operator duopoly.
Yet the real test comes later this year. Football season will determine whether Ohio’s handle growth resumes its upward trajectory or whether the market has found its natural ceiling for year-two performance.
Behavioral Patterns Shaping Ohio’s Betting Market
Beyond the financial metrics, what’s unfolding in Ohio reflects broader behavioral shifts in how Americans engage with sports betting. The transition from novelty to routine is a critical inflection point for any regulated market. Early adopters driven by curiosity and promotional incentives give way to a core user base that bets with regularity, often across multiple sports and bet types.
This behavioral maturation has implications for responsible gambling frameworks as well. Habitual bettors are more likely to encounter sustained losses over time, and Ohio’s regulators face the challenge of balancing revenue optimization with consumer protection mandates. The state’s problem gambling fund, supported by a portion of tax revenue, will need to scale alongside market participation. Operators, for their part, have begun integrating more sophisticated self-exclusion tools and deposit-limit features, though adoption rates for these tools remain low industry-wide. How effectively Ohio bridges the gap between available safeguards and actual bettor behavior could set a precedent for other states watching from the sidelines. The psychological dimension of betting engagement, where loss aversion and reward anticipation drive repeat activity, demands regulatory attention that goes beyond simple revenue reporting.
Frequently Asked Questions
How much tax revenue has Ohio generated from sports betting?
Since launching in January 2023, Ohio has collected tens of millions in sports betting tax revenue. The exact cumulative figure fluctuates monthly, but the 10% rate applied to adjusted gross revenue has produced a consistent stream of state income, even during traditionally slower sports months like May.
Why did Ohio’s tax revenue grow even though handle stayed flat?
Higher operator hold rates and reduced promotional credit usage are the most likely explanations. When sportsbooks retain more of each wager and spend less on bonuses, the taxable revenue base expands without requiring additional betting volume.
Is Ohio’s sports betting market considered mature?
At roughly 17 months post-launch, Ohio sits in the transition zone between early growth and maturity. The flattening of handle growth alongside improving revenue efficiency suggests the market is moving past its initial expansion phase, though football season will provide a clearer benchmark.