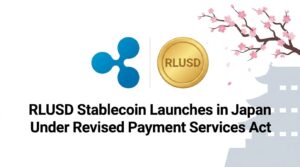
Ripple’s RLUSD stablecoin began trading in Japan on Wednesday, June 25, following approval from the country’s Financial Services Agency (FSA). The launch, announced jointly by Ripple and SBI Holdings, positions RLUSD as one of the first foreign-issued stablecoins to be classified under Japan’s revised Payment Services Act. That distinction carries weight: Japan has long maintained one of the strictest regulatory frameworks for digital assets in Asia, and gaining FSA clearance is no small feat for any token issuer, domestic or otherwise.
What RLUSD’s Japan Entry Signals for the Stablecoin Market
Before diving into the strategic implications, it’s worth framing what this launch actually represents. Japan’s stablecoin regulations, updated in 2023, require issuers to back tokens with fiat reserves held in Japanese trust accounts and to comply with anti-money laundering obligations that mirror those applied to traditional banking. For a U.S.-headquartered company like Ripple to satisfy those conditions suggests a level of institutional readiness that few crypto-native firms have demonstrated in the Japanese market.
- Regulatory precedent: RLUSD’s FSA approval makes it among the earliest foreign-issued stablecoins to operate legally under Japan’s revised payments framework, setting a template for competitors eyeing the same market.
- SBI Holdings as distribution partner: Ripple’s alliance with SBI Holdings, one of Japan’s largest financial conglomerates, gives RLUSD immediate access to institutional and retail distribution channels that would take years to build independently.
- The launch could accelerate cross-border payment corridors between Japan and other markets where RLUSD already circulates, particularly the United States.
- Competitive positioning: With Tether (USDT) and Circle’s USDC still navigating Japan’s regulatory requirements, RLUSD has a narrow but meaningful first-mover window.
Why Japan, and Why Now?
Japan’s appetite for regulated digital assets has grown steadily since the FSA began tightening oversight after the 2018 Coincheck hack. The revised Payment Services Act, which took effect in June 2023, created a legal category specifically for stablecoins pegged to fiat currencies. But the regulatory bar is high. Issuers must partner with licensed intermediaries, maintain full reserve backing, and submit to ongoing FSA audits.
Ripple’s partnership with SBI Holdings’ financial services ecosystem predates this stablecoin launch by several years. The two companies have collaborated on cross-border remittance solutions through SBI Remit since 2016, giving Ripple an embedded relationship with a firm that already holds the necessary licenses. That history arguably made Japan a more natural entry point for RLUSD than markets where Ripple lacks comparable institutional footing.
Still, the timing raises questions. Ripple launched RLUSD globally in December 2024, initially targeting the U.S. and select international markets. A six-month gap before entering Japan suggests the FSA approval process was neither fast nor automatic (a distinction regulators have been slow to publicize).
How Japan’s Stablecoin Rules Compare
| Requirement | Japan (Revised PSA) | United States (Proposed Frameworks) |
|---|---|---|
| Reserve backing | Full fiat reserves in Japanese trust accounts | Varies by proposed bill; generally 1:1 fiat or Treasuries |
| Issuer licensing | Must be a licensed bank, trust company, or funds transfer agent | No unified federal license yet; state-level varies |
| AML/KYC obligations | Equivalent to banking-sector standards | FinCEN guidance applies, but enforcement is inconsistent |
| Foreign issuer access | Permitted through licensed domestic partners | No clear pathway established at federal level |
| Audit requirements | Ongoing FSA oversight and periodic audits | Proposed but not yet codified in most draft legislation, with details still under debate in Congress |
The contrast is stark. Japan has a functioning, enforceable framework. The U.S., at least on paper, is still debating what one should look like.
The SBI Factor: Distribution Without Friction
SBI Holdings is not a passive partner in this arrangement. The conglomerate operates SBI VC Trade, a registered crypto exchange, alongside banking, securities, and insurance subsidiaries. RLUSD’s distribution through SBI’s channels means the stablecoin can reach users who already hold accounts within a regulated financial ecosystem, bypassing the onboarding friction that plagues standalone crypto platforms.
And while Ripple provides the token infrastructure, SBI’s role as the domestic intermediary satisfies the FSA’s requirement that stablecoins be distributed through licensed entities. This model, where a foreign issuer pairs with a domestic financial institution, could become the default pathway for other stablecoin projects seeking Japanese market access. Whether competitors can replicate it without similarly deep local partnerships remains an open question.
Cross-Border Payment Implications
RLUSD’s presence in Japan opens a corridor that Ripple has been building toward for years. Japan is the world’s third-largest economy and a major hub for remittance flows to Southeast Asia. If RLUSD gains traction as a settlement layer for these transfers, it could reduce costs and processing times compared to traditional correspondent banking networks.
But traction is not guaranteed. Japanese consumers and businesses have historically shown limited enthusiasm for crypto-denominated payments, preferring established rail systems like Zengin. Ripple’s bet is that institutional adoption through SBI’s network will create enough liquidity to make RLUSD viable for commercial use cases, not just speculative trading.
Frequently Asked Questions
What is RLUSD?
RLUSD is a stablecoin issued by Ripple, pegged 1:1 to the U.S. dollar and backed by fiat reserves. It launched globally in December 2024.
Why does Japan’s approval matter?
Japan operates one of the most rigorous regulatory regimes for digital assets globally. FSA approval under the revised Payment Services Act signals that RLUSD meets banking-grade compliance standards, which could influence how other jurisdictions evaluate the token.
Can other stablecoins like USDT or USDC operate in Japan?
Not yet under the current framework, at least not in a fully licensed capacity. Both Tether and Circle would need to secure FSA approval and partner with licensed domestic intermediaries. RLUSD’s early entry gives Ripple a competitive edge that may prove difficult to close quickly.
How does this affect XRP?
RLUSD and XRP serve different functions within Ripple’s ecosystem. RLUSD is a fiat-pegged stablecoin designed for payments and settlement, while XRP operates as a bridge asset. The two are complementary rather than competing, though how the market prices that distinction is another matter entirely.