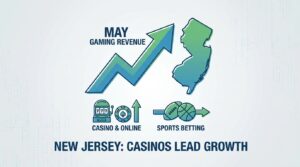
New Jersey’s regulated gaming market posted another month of year-over-year revenue growth in May 2025, though the composition of that growth tells a more nuanced story than the topline figure suggests. While internet gaming and Atlantic City’s land-based casinos pushed the state’s total gaming revenue higher, sports betting revenue declined compared to the same period a year ago. The shift underscores a broader recalibration in how New Jersey’s gaming ecosystem generates its returns, with digital casino play now firmly established as the dominant revenue driver.
What May’s Numbers Reveal About New Jersey’s Gaming Mix
Before diving into the specifics, the strategic picture is worth framing. New Jersey remains one of the most mature regulated gaming markets in the United States, and its monthly revenue reports function as a barometer for broader industry trends. May’s data reinforces several dynamics that executives and regulators should be tracking closely.
- Internet gaming continues to outperform: Online casino revenue maintained its upward trajectory, compensating for softness in sports wagering and reinforcing iGaming’s role as the state’s most reliable growth vertical.
- Sports betting handle remained substantial, but margins compressed, dragging operator revenue lower year-over-year.
- Atlantic City brick-and-mortar casinos posted modest gains, a signal that in-person visitation has stabilized rather than declined further post-pandemic.
- The overall revenue mix is tilting further toward digital channels, a trend with implications for tax policy, licensing strategy, and competitive positioning among operators.
- New Jersey’s market maturity may be approaching a plateau in sports betting, even as iGaming headroom persists
Sports Betting: High Volume, Thinner Margins
May is not traditionally a peak month for sports wagering. The NFL season is months away, and while the NBA and NHL playoffs generate action, they lack the sheer volume of football weekends. Still, the decline in sports betting revenue wasn’t purely seasonal.
Operators across New Jersey reported healthy handle figures, meaning bettors were active. The issue was hold percentage. Sportsbooks kept a smaller share of the money wagered, which translated directly into lower gross gaming revenue. That dynamic (a distinction worth watching over multiple months rather than reacting to in isolation) has surfaced repeatedly in mature U.S. sports betting states. Promotional spending, competitive odds, and bettor sophistication all contribute to margin pressure.
Whether this represents a structural shift or a one-month variance remains an open question. But for operators managing P&L across multiple states, New Jersey’s sports betting line item is no longer the growth story it was in 2021 and 2022.
iGaming Carries the Weight
Internet gaming revenue told a different story entirely. The segment has grown almost every month for the past two years in New Jersey, and May continued that streak. Online slots, table games, and peer-to-peer poker all contributed, with slots generating the bulk of the revenue as usual.
New Jersey was among the first states to legalize online casino gaming, launching in 2013. That head start has given operators time to refine acquisition funnels, optimize game libraries, and build habitual user bases. The result: a market where New Jersey’s online casino operators benefit from compounding engagement rather than relying on new customer acquisition alone. And while other states have since entered the iGaming space, few match New Jersey’s depth of product or regulatory sophistication.
One data point worth noting is the gap between iGaming’s contribution and sports betting’s contribution to total digital revenue. That gap widened again in May. For legislators in states still debating whether to authorize online casino play alongside sports betting, New Jersey’s numbers make a compelling fiscal case.
Atlantic City’s Quiet Stabilization
Land-based casino revenue in Atlantic City edged higher in May, though not dramatically. The city’s nine casinos have largely found a floor after years of contraction and consolidation. Visitation patterns suggest a mix of regional day-trippers and weekend tourists, with midweek traffic still softer than pre-pandemic levels.
Hard Rock, Borgata, and Ocean Casino Resort continued to lead the pack. Smaller properties face tighter margins and greater sensitivity to weather, events, and gas prices. Yet even the lower-performing casinos avoided sharp declines, which counts as progress given the competitive landscape.
How Market Maturity Reshapes Operator Strategy
New Jersey’s gaming market has entered a phase where growth comes from optimization, not expansion. That shift carries real strategic consequences for operators, investors, and regulators alike. Understanding the behavioral and psychological dimensions of player engagement becomes critical in this environment.
Operators increasingly rely on personalization engines that segment players by risk tolerance, session frequency, and game preference. These systems draw on principles that parallel neuro-linguistic programming frameworks: anchoring users to specific experiences, framing promotional offers in terms of perceived value rather than raw dollar amounts, and using sequencing techniques in bonus structures to sustain engagement loops. The language of push notifications, the timing of re-engagement emails, the visual hierarchy of a lobby page — all of these are calibrated to influence decision-making at a subconscious level.
Responsible gaming advocates have raised questions about where personalization ends and manipulation begins. New Jersey’s Division of Gaming Enforcement has been more active than most state regulators in scrutinizing marketing practices, but the tools operators deploy are evolving faster than the oversight frameworks designed to govern them. In practice, the line between a well-designed user experience and a psychologically coercive one is blurrier than either side typically acknowledges.
For investors, the implication is that customer lifetime value metrics matter more than top-of-funnel acquisition numbers in a mature market. Operators who can retain and monetize existing players efficiently will outperform those still spending heavily on sign-up bonuses with diminishing returns. The economics of New Jersey’s market increasingly reward behavioral intelligence over brute-force marketing spend.
Frequently Asked Questions
Did New Jersey’s total gaming revenue increase in May 2025?
Yes. Total gaming revenue grew year-over-year, driven primarily by internet gaming and modest gains from Atlantic City’s land-based casinos.
Why did sports betting revenue decline?
Handle remained strong, but sportsbook hold percentages dropped, meaning operators retained a smaller share of the money wagered. Seasonal factors and competitive margin pressure both played a role, though the relative weight of each is difficult to isolate from a single month’s data.
Which segment contributed most to New Jersey’s gaming revenue?
Internet gaming — specifically online slots and table games — was the largest contributor and the fastest-growing segment.
Is New Jersey’s sports betting market shrinking?
Not in terms of betting volume. Bettors are still active. But revenue growth has stalled, and margins are under pressure. Whether that’s cyclical or structural is the question operators are trying to answer.
How does New Jersey compare to other U.S. gaming states?
New Jersey remains one of the most mature and diversified regulated gaming markets in the country, with a longer track record in iGaming than nearly any other state. Its data often serves as a leading indicator for newer markets.