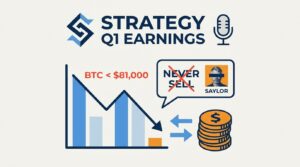
Strategy, the enterprise software firm turned Bitcoin treasury vehicle formerly known as MicroStrategy, rattled crypto markets during its Q1 2025 earnings call by signaling a potential shift away from Michael Saylor’s long-held “never sell” stance on Bitcoin. The disclosure came as Bitcoin slid below $81,000, amplifying investor unease. For a company that has staked its identity on aggressive BTC accumulation, even a rhetorical softening carries weight across digital asset markets and institutional sentiment alike.
What Strategy’s Earnings Call Actually Revealed
Before unpacking the strategic implications, it helps to isolate what changed. The key takeaways below distill the business-level signals from the Q1 call and the market’s immediate reaction.
- Rhetorical pivot on selling: Strategy’s leadership acknowledged, for the first time publicly, that liquidating a portion of its Bitcoin holdings could become a viable option under certain financial pressures, a notable departure from Saylor’s absolutist accumulation doctrine.
- Bitcoin dropped below $81,000 in the hours following the call, a decline that coincided with broader macro headwinds but was accelerated by the earnings commentary.
- Balance sheet exposure: With over 214,000 BTC on its books (a figure that has grown quarter over quarter), even modest language shifts about disposition strategy ripple through institutional risk models.
- The company’s stock experienced heightened volatility, reflecting uncertainty about whether this marks a tactical adjustment or a fundamental change in treasury philosophy.
- Analysts flagged the disconnect between Strategy’s debt-funded accumulation model and the possibility of forced selling during a prolonged downturn.
Why the “Never Sell” Doctrine Mattered So Much
Saylor’s commitment to holding Bitcoin indefinitely wasn’t just a personal conviction. It functioned as a market signal. Institutional investors who allocated capital to Strategy’s Bitcoin-centric treasury model did so partly because the company’s unwillingness to sell created a perceived floor of demand. Remove that certainty, and the calculus shifts.
The doctrine also served a structural purpose. By pledging never to sell, Strategy effectively told creditors and convertible note holders that its BTC stack was a long-duration asset, not a trading position. That framing supported the company’s ability to raise capital at favorable terms. Whether the Q1 language change alters those terms going forward remains an open question (and one that bond markets will answer faster than equity analysts).
Bitcoin Below $81,000: Coincidence or Consequence?
Attributing Bitcoin’s dip solely to one company’s earnings call would be an oversimplification. Macro factors, including persistent rate uncertainty and softening risk appetite across equities, were already pressing on crypto prices. Still, the timing was hard to ignore.
Strategy holds roughly 1% of all Bitcoin that will ever exist. That concentration gives its treasury decisions outsized influence on market psychology, particularly among institutional holders who track whale wallet behavior and corporate disclosure language with equal intensity. A single sentence about potential selling from a company of this scale can move sentiment faster than a Fed dot plot.
| Metric | Q1 2025 | Q4 2024 |
|---|---|---|
| BTC Holdings (approx.) | 214,000+ BTC | ~190,000 BTC |
| BTC Price at Earnings | Below $81,000 | ~$94,500 |
| Stock Volatility (post-call) | Elevated | Moderate |
| Debt-Funded Acquisition Pace | Continued but under scrutiny | Aggressive |
The Debt Structure Behind the Rhetoric
Strategy has financed much of its Bitcoin buying through convertible notes and at-the-market equity offerings. That model works beautifully when BTC appreciates. When it doesn’t, the math tightens. And the Q1 commentary suggests management is at least acknowledging scenarios where the math could force a hand.
This isn’t panic. But it is realism. The company’s debt obligations don’t disappear during drawdowns, and servicing those obligations while Bitcoin trades sideways or lower introduces pressure that a “never sell” posture cannot absorb indefinitely. In practice, the shift may be less about intent and more about disclosure risk: telling investors you will never sell an asset you might need to sell creates legal exposure that no CFO wants to carry into a downturn.
How Institutional Holders Should Read This Signal
For portfolio managers and corporate treasurers watching Strategy as a proxy for Bitcoin conviction, the Q1 call introduces a layer of ambiguity that didn’t previously exist. That ambiguity has practical consequences.
Risk models that assumed Strategy’s BTC was permanently off-market now need revision. Convertible note pricing may adjust. And the broader narrative that corporate Bitcoin adoption is a one-way door loses some of its force. Yet none of this necessarily means Strategy will sell. The gap between acknowledging a possibility and executing on it remains wide. What changed is the permission structure around the conversation itself.
Frequently Asked Questions
Did Strategy actually sell any Bitcoin in Q1 2025?
No confirmed sales have been disclosed. The shift was rhetorical, not transactional, but markets reacted to the change in tone as a forward-looking signal.
How much Bitcoin does Strategy currently hold?
The company holds over 214,000 BTC as of its Q1 2025 reporting, making it the largest publicly traded corporate holder of Bitcoin globally.
Why did Bitcoin fall below $81,000 after the call?
Multiple factors contributed, including macroeconomic uncertainty and broader risk-off sentiment. Strategy’s earnings commentary added a company-specific catalyst that intensified selling pressure in an already fragile market.
Could Strategy be forced to sell Bitcoin to meet debt obligations?
Under extreme scenarios involving prolonged BTC price declines and tightening credit conditions, the possibility exists. The company has not indicated imminent need, but acknowledging the scenario publicly was itself a significant development.
What does this mean for other companies holding Bitcoin on their balance sheets?
It complicates the narrative. Companies considering Bitcoin treasury strategies will now weigh not just the asset’s volatility but the reputational and disclosure risks of rigid holding commitments. The playbook Saylor popularized may still work, but it no longer looks as simple as it once did.