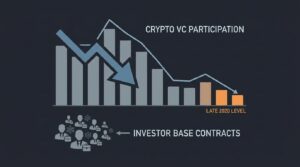
Only 150 unique venture capital firms took part in crypto funding rounds through July 28, marking the lowest monthly count since November 2020, according to data compiled by CryptoRank. The collapse in active investor count underscores a dramatic contraction from the May 2022 peak, when 1,177 distinct VC firms participated in deals across the digital asset ecosystem. That’s an 87% decline in unique participants over roughly two years. For founders seeking capital and LPs evaluating exposure, the signal is hard to misread.
What the VC Pullback Reveals About Crypto Capital Markets
Before diving into the strategic implications, it’s worth framing what this data point actually represents. The number of unique firms participating in rounds is not the same as total capital deployed; a smaller pool of investors can still write large checks. But the breadth of the investor base matters enormously for deal flow, valuation competition, and the diversity of strategic support available to early-stage projects. When that base shrinks this severely, the downstream effects ripple through hiring, product timelines, and market structure itself.
- Investor concentration risk is rising. With fewer than 150 firms active, deal-making power consolidates among a small cohort. Founders face fewer term sheet options and potentially less favorable terms.
- Late-2020 comparisons carry weight. November 2020 preceded the explosive growth phase of DeFi and NFT-driven capital formation. The current figure suggests the market has, at least on paper, returned to pre-boom participation levels.
- The 87% decline from May 2022’s peak of 1,177 unique firms is not gradual attrition. It reflects a structural exit by hundreds of funds that entered crypto during the bull cycle and have since either wound down, pivoted, or paused deployment.
- Surviving firms hold outsized influence over which sectors, protocols, and geographies receive funding, shaping the next cycle’s winners before it begins.
- Regulatory uncertainty in the U.S. continues to suppress new fund formation specifically targeting digital assets, even as spot Bitcoin ETFs attract institutional flows elsewhere in the stack.
How the Contraction Compares Across Cycles
Crypto venture capital has always been cyclical, but the speed and depth of this drawdown stand apart. During the 2018–2019 downturn, VC participation declined meaningfully, yet the ecosystem’s overall footprint was far smaller. The 2021–2022 boom attracted a wave of generalist funds, crossover investors, and newly formed crypto-native vehicles, many of which deployed aggressively into categories like GameFi, layer-1 infrastructure, and centralized exchange equity.
Most of those entrants are gone.
What remains is a core of committed crypto-native firms alongside a handful of generalist players with dedicated blockchain practices. The distinction matters because crypto-native VCs tend to offer more than capital (a point that sounds like marketing until you watch a protocol navigate a regulatory inquiry without experienced board-level guidance). Still, the sheer reduction in competitive pressure among investors raises questions about whether valuations have overcorrected or whether founders are simply building with less.
| Period | Unique VC Firms Active | Market Context |
|---|---|---|
| November 2020 | ~150 | Pre-DeFi summer afterglow; Bitcoin approaching $20K |
| May 2022 | 1,177 | Peak bull market; Terra/Luna collapse weeks away |
| July 2025 (through July 28) | 150 | Post-ETF approval; regulatory frameworks still evolving across major jurisdictions |
Why Fewer Investors Doesn’t Necessarily Mean Less Capital
A nuanced reading of the data requires separating participation breadth from deployment depth. Several of the most active crypto venture firms, including those tracking deal flow and fundraising analytics on CryptoRank, have reported that round sizes for infrastructure and middleware projects remain competitive. Mega-rounds above $50 million have not disappeared entirely; they’ve just become rarer and more concentrated.
And while total disclosed funding has declined year-over-year, the capital that is flowing tends to target a narrower set of verticals: zero-knowledge infrastructure, restaking protocols, stablecoin payments, and AI-crypto intersections. Generalist enthusiasm for “web3 social” or play-to-earn has largely evaporated. That filtering effect arguably produces a healthier allocation landscape, though it also means entire categories of innovation lose access to institutional backing.
The Psychology Behind Capital Retreat
Understanding why hundreds of VC firms exited crypto requires looking beyond balance sheets. Behavioral patterns in venture capital follow recognizable cycles of conviction and disillusionment that mirror broader decision-making frameworks studied in neuro-linguistic programming and behavioral economics. During the 2021 boom, social proof mechanisms drove rapid fund formation: when prominent endowments and pension funds signaled crypto exposure, smaller allocators followed, anchoring their risk tolerance to the perceived safety of the herd.
That anchoring reversed violently after the collapses of FTX, Terra/Luna, and Three Arrows Capital. Loss aversion, one of the most powerful cognitive biases in capital allocation, pushed LPs to withdraw mandates and GPs to pause deployment even in cases where portfolio fundamentals remained intact. The reputational cost of being associated with crypto losses created what behavioral researchers call an “availability cascade,” where a few high-profile failures became the dominant mental model for an entire asset class.
Reframing that narrative takes time. The firms still active in July 2025 have, in most cases, undergone an internal recalibration: tighter investment theses, longer diligence cycles, and a deliberate shift away from momentum-driven deployment. For founders, this means the pitch process has changed fundamentally. Investors now pattern-match against sustainability metrics and regulatory readiness rather than total addressable market projections built on speculative adoption curves. The psychological contract between founder and funder has, in effect, been rewritten.
What happens when participation rebounds?
History suggests that VC participation tends to lag price recovery by six to twelve months. Bitcoin’s price action in 2024 and early 2025, driven partly by ETF inflows, has not yet translated into a meaningful expansion of the active investor base. Whether that lag is structural this time, or simply a matter of timing, is the question no one can answer with confidence yet.
Frequently Asked Questions
Why has the number of crypto VC firms dropped so sharply?
A combination of fund lifecycle dynamics, LP pressure following high-profile collapses like FTX, and persistent regulatory ambiguity in key markets has pushed hundreds of firms to exit or pause crypto-focused deployment. Many generalist funds that entered during the bull market have not returned.
Does fewer VC participation mean less money flowing into crypto startups?
Not directly. Fewer firms can still deploy significant capital, and some active investors have increased their check sizes. But the reduction in competitive tension among investors likely affects valuations and term structures for founders.
Which crypto sectors are still attracting venture funding?
Zero-knowledge proof infrastructure, restaking protocols, stablecoin payment rails, and projects at the intersection of AI and blockchain continue to draw institutional interest. Categories like GameFi and web3 social have seen sharp declines in new investment.
When might VC participation recover?
Historically, investor participation lags asset price recovery by roughly six to twelve months. Regulatory clarity, particularly in the United States, could accelerate re-entry. But some of the firms that left during the downturn have wound down permanently, meaning the next wave may look quite different from the last one.



